
If you are living on a fixed income, the question “how much does it cost to start an online business” deserves a real answer before you sign up for anything. Most online money advice assumes a paycheck that keeps arriving, no matter what you spend. Yours does not work that way, so the order of decisions matters: set the limit first, then look at what you might buy.
This guide goes through the likely costs line by line, the ones you can safely skip, and where Wealthy Affiliate fits as a single line in the budget. It does not quote prices, because prices change and you should read them on the seller’s own page on the day you decide. It also does not promise income. An online business can earn nothing, especially at the start, so the plan below assumes that and protects you accordingly.
If you are still deciding whether earning online suits you at all, this starting-point post on online income for retirees covers that question first.
Quick answer
There is no set cost to start an online business. Your budget may include a domain, hosting, training, and optional tools. Set a monthly limit you can afford to lose, count yearly fees as monthly costs, and start with free resources where you can.
Why a budget matters more when your income is fixed
A working person who spends too much on a failed project can usually make it back over the following months. A retiree drawing on a pension, Social Security or savings often cannot. Money spent on a venture that does not pay off comes out of the same pool that covers groceries, insurance and the electric bill.
That does not mean you should stay away. It means the downside should be small enough that you could lose all of it and your daily life would not change. Starting an online business is a slow process. Websites take months to attract readers, and affiliate commissions only arrive once readers trust you enough to act on a recommendation. Plan your spending around that timeline, not around the hope of an early payoff.
A budget also protects you from the sales pitches that are common in this area. Many of them are built on urgency: a countdown clock, a “last chance” discount, a bonus that disappears at midnight. If you already have a number written down, you can compare any offer to it calmly and decline anything that does not fit.
Set your ceiling first: the monthly amount you can spend without worry
Your ceiling is the most you will spend on this project each month. Pick it before you look at a single product page.
A practical way to find it is to look at your last two or three months of bank statements and note what is left after all fixed bills and normal spending. Then decide how much of that leftover you would be comfortable never seeing again. That amount, or something smaller, is your ceiling. A good test is whether spending it would cost you any sleep. If it would, lower it.
Some rules that keep the ceiling useful:
- Count everything that recurs: membership fees, hosting, tools, email services, and any subscription you sign up for along the way.
- Convert yearly charges to a monthly figure. A domain or hosting plan billed once a year still takes money from you, and it is easy to forget until the renewal arrives.
- Keep the ceiling out of your emergency savings and out of money earmarked for medical costs.
- Do not borrow to start, and do not put start-up costs on a credit card you cannot pay off in full that month.
Your ceiling can be low. Many people begin with very little, because the first stage of an online business is learning and writing, not buying.
Before you spend, set your guardrails
- Choose a monthly limit you could afford to lose.
- Keep the money separate from emergency and medical savings.
- Count yearly charges as part of your monthly budget.
- Do not borrow or carry a balance on a credit card to get started.
If the spending would cost you sleep, lower the limit.
The costs you can expect: hosting, a domain, tools, and training
Most online businesses built around a website or blog have the same handful of cost categories. Some of them can be zero or close to it at the start.
A domain name
A domain is your site’s address, such as yourname.com. You rent it, usually for a year at a time, and the registrar charges a renewal fee each year. Prices vary by registrar and by the extension you choose, and renewal prices are sometimes higher than the first-year price. Read both numbers before you buy.
Hosting
Hosting is the service that keeps your website available on the internet. Some platforms bundle it into a membership, and some sell it separately. Either way, it is a recurring cost and belongs in your monthly total. If a platform says hosting is included, ask what exactly that covers, how many sites it allows, and what happens to your site if you cancel.
Tools
Depending on how you work, you may want some of these:
- A keyword research tool, to see what people are searching for
- An email service, to send updates to readers who sign up
- An image editor or image generator for pictures on your pages
- A writing assistant
Many tools have free versions that are plenty for a beginner. Start with those. Upgrade only when you hit a limit that is actually slowing you down, not because a paid tier looks more professional.
Training
You will need to learn how to build a site, write useful articles, and promote products honestly. Training can be free, built into a membership, or sold as a separate course. This is the line where retirees most often overspend, so look carefully at what you are paying for and whether the same material is already included elsewhere.
A quick check of your monthly budget
Membership or training: Use the current cost, or zero for a free option.
Domain: Divide the yearly charge by 12.
Hosting: Include it separately, or count it as included if it is bundled.
Tools and other costs: Add any paid software, books, or courses you choose.
Add the lines together. If the total is above your ceiling, postpone or remove optional costs.
Costs that people forget
Two items sit outside the usual lists. The first is your time, which has no price but is limited. The second is tax and benefits. Income from an online business is generally reportable, and expenses may or may not be deductible depending on where you live. If you claim Social Security before your full retirement age, earnings can also affect your benefit. A short conversation with a tax professional or the Social Security Administration before you earn anything is cheap and worth having.
The costs you can skip: expensive courses, gadgets and “guru” upsells
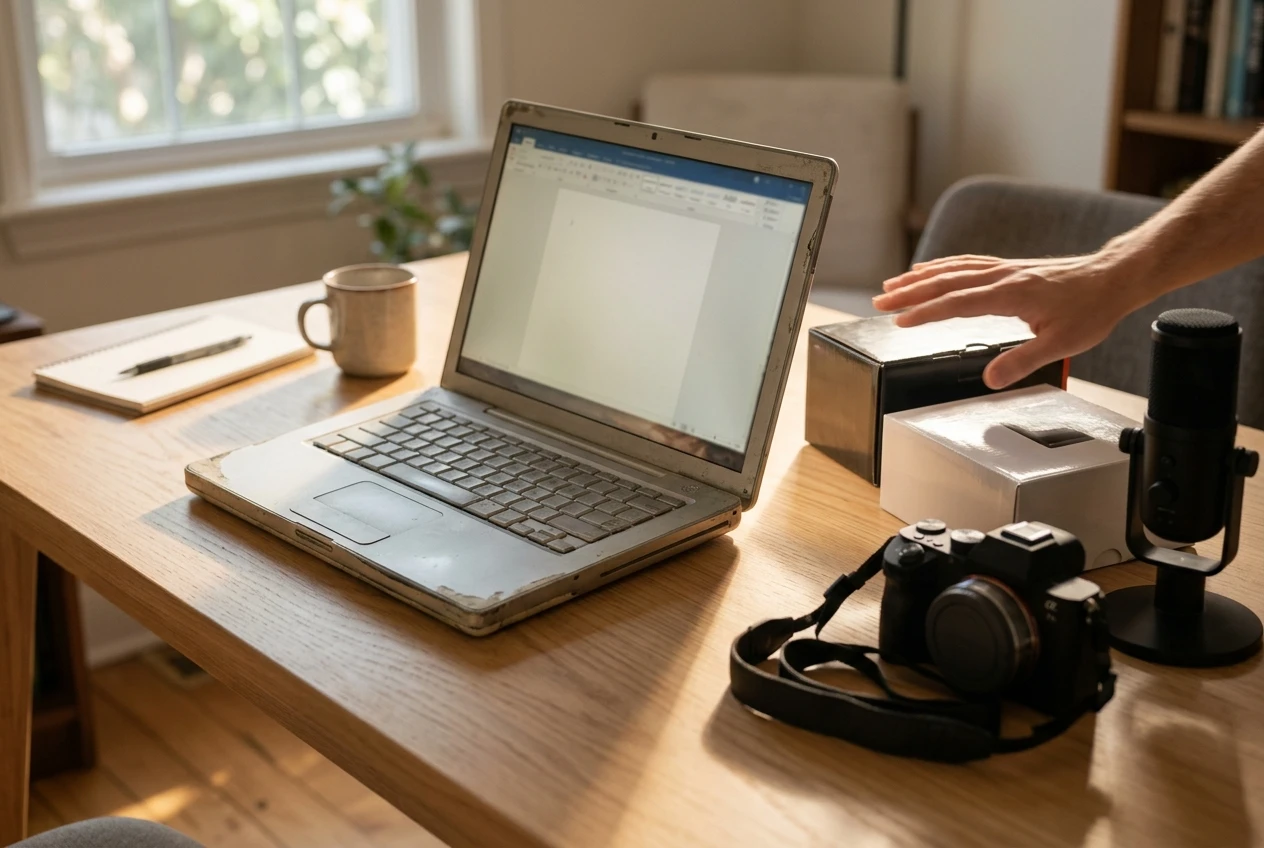
Spending nothing is not the goal. The goal is to spend only on what moves you forward. Here is what usually does not.
Expensive stand-alone courses. A high-priced course is not better because it costs more. If a seller will not show you the full outline, the instructor’s credentials, and a clear refund policy, treat that as an answer. Be especially careful with courses that promise a specific income. Nobody can promise that honestly, because results depend on the person, the niche, and a good deal of time.
New equipment. A basic computer or tablet that you already own, with a steady internet connection, is enough to write articles and run a website. You do not need a new camera, a microphone or a second monitor to start. If a particular need comes up later, buy for that need then.
Upsells after the first purchase. Many offers begin with a low price and then present a series of “one-time” add-ons on the checkout pages. Decide in advance that you will decline all of them. If an add-on really is useful, it will still be available next week, when you have had time to compare it with your budget.
Software bundles and “done for you” sites. Pre-built websites and large software packages often cost more than doing the work yourself in a plain, well-supported platform, and they leave you with a site you do not understand.
Paid traffic. Buying advertising can lose money quickly even for experienced marketers. On a fixed budget, put it off until you have something that already earns.
A simple rule: if you cannot explain in one sentence what a purchase will let you do that you cannot do now, do not buy it yet.
Where Wealthy Affiliate fits as one line in your budget
Wealthy Affiliate is a membership platform that teaches affiliate marketing and gives members tools for building a website. This site promotes it and earns a commission when a reader joins through one of its links, so weigh my view with that in mind. The fairest way to think about it is as one line in your budget, to be judged against your ceiling like every other line.
A membership should pass your budget check
This site earns a commission when readers join through its links. Use the official membership page to check the details for yourself.
- Try the free Starter membership before paying.
- Check the current price, billing period, and renewal cost.
- Confirm what the membership includes and how cancellation works.
- Join only if the cost stays within your spending ceiling.
Here is what to check before you join, using the membership page itself rather than anyone’s summary, mine included:
- What the free starter membership includes. Find out what you can do and see without paying, and whether there is a time limit on it. This lets you try the training and the way the platform works before spending anything.
- The current price of each paid level. Read it on the official page on the day you decide, and check whether it is billed monthly or yearly.
- What is covered by the fee. Look for whether training, hosting, website building, live classes and the writing and image tools are included, and whether any of them use credits that you can run out of.
- What renewal costs. A first-period price can differ from the price after it.
- How cancellation works. Know how you cancel, when the cancellation takes effect, and what happens to a website you have built.
- Whether the training fits how you learn. Some people like short video lessons and live sessions. Others prefer to read at their own pace. Try a few lessons from the free level and notice whether you finish them.
Then compare the total monthly cost with your ceiling. If the paid membership fits inside it with room to spare, it may be a reasonable line. If it would push you over, wait, stay on the free level, or choose a cheaper way to learn. Wealthy Affiliate does not have to be the answer to everything, and a retiree who decides it is not the right fit has made a sound decision rather than a missed one.
Curious if Wealthy Affiliate fits your budget?
Take a look at the free Starter membership and see what’s included. No rush to upgrade. Choose only what feels right for your budget.
Explore the Starter membershipPick your stop-loss date: how long to give it before you reassess
A stop-loss date is a calendar date, chosen in advance, on which you sit down and decide whether to continue, change the plan or stop. It works because it takes the decision away from your mood on a bad day or your optimism on a good one.
To set it, multiply your monthly ceiling by the number of months you are willing to try. That product is the most you will have spent by the review date. If the number feels uncomfortable, shorten the period or lower the ceiling until it does not.
Online businesses built on content tend to need many months before the results say anything useful, so a very short window, such as a few weeks, will mostly tell you that it is too early. A longer window, such as six months to a year, gives the work a fair chance without leaving the spending open-ended. Pick the length that matches your finances and write the date on a calendar where you will see it.
On that date, ask three questions:
- How much have I spent in total, and was it within the ceiling?
- What have I finished? Count articles published, lessons completed, and visitors recorded.
- Is there any income, however small, and is the trend rising?
If the work is moving and the spending is under control, you might extend the date by a few months with the same ceiling. If you have spent the full amount and have little to show, stopping is a perfectly good outcome. You will have spent a known sum to learn something real, and you did not put your retirement at risk to find out.
Your stop-loss check
Monthly ceiling × months you choose = maximum planned spend
Write down your monthly ceiling.
Choose a date to review your progress.
At that date, check spending, completed work, and any income.
If the total feels uncomfortable, lower the ceiling or shorten the trial period.
A simple one-page budget you can fill in tonight
You need one sheet of paper or a basic spreadsheet. Write these lines down the left side, and put a monthly amount beside each one:
- Monthly ceiling: the number you chose earlier.
- Membership or training: the monthly cost of any paid plan, or zero if you are on a free level.
- Domain: the yearly price divided by twelve.
- Hosting: the monthly cost, or the yearly price divided by twelve, or zero if it is bundled.
- Tools: the total for any paid software.
- Other: anything else, such as a book or a one-off course you have decided is worth it.
- Total planned spending: the sum of the lines above.
- Room left under the ceiling: the ceiling minus the total.
- Stop-loss date: the calendar date of your review.
- Maximum total spend by that date: the ceiling multiplied by the number of months until then.
If the total planned spending is higher than the ceiling, remove or postpone lines until it is not. Start with the lines at the bottom of the list, because those are the ones most likely to be optional.
Tracking what comes in and what goes out, month by month
Once you have started, keep a record. It takes about ten minutes at the end of each month, and it is the only way your stop-loss review will rest on facts instead of impressions.
Use two columns of figures for each month. In the first, list every payment you made for the project, with the date, the payee, and the amount. In the second, list any money received, noting where it came from. Keep the receipts or confirmation emails in a single folder so that you have them if you need them for taxes.
At the end of each month, calculate three numbers: total spent, total earned, and the running total of both since you began. Compare the total spent with your ceiling. If you went over, find out which line caused it and fix it before the next month starts.
Note, too, the work you did. A short list is enough: how many articles you wrote, what you published, which lessons you finished. Early on, this work record often matters more than the income figure, because the income lags behind the work by a long way. When your review date arrives, you will have a clear record of the money and the effort, and the decision will be much easier to make.
Before you spend anything, check what Wealthy Affiliate offers on its free starter membership and see whether it suits the budget you just set. Then take a look at my earlier post on starting without tech skills.
A simple month-end check-in
- List project payments and any income received.
- Save receipts and confirmation emails in one folder.
- Add up total spending, earnings, and your running totals.
- Note what you completed, such as articles published or lessons finished.
- Compare spending with your ceiling before the next month begins.
Ten minutes of record-keeping can make your review date easier to handle.
FAQs About Starting an Online Business on a Retirement Budget
How much does it cost to start an online business?
There is no single start-up cost for every business. Your expenses depend on the platform and tools you choose. List costs such as a domain, hosting, training, and optional tools. Convert yearly charges to monthly amounts, then keep the total within a limit you can afford to lose.
Can I start an online business on a fixed income?
You can explore the idea while protecting your fixed income. Set a monthly spending ceiling first, keep that money separate from emergency and medical savings, and avoid borrowing or carrying credit card debt for start-up costs. Free resources can help you learn before you commit money.
What expenses might I need to start an online business?
Common costs may include a domain name, website hosting, training, and tools such as keyword research or email software. Some may be free or included in a membership. Check what is included, what renews, and what you would need to pay for separately.
Can I start without paying for courses or tools?
Often, yes. Free lessons and tool plans may be enough to get started. Use what you already own, and pay for an upgrade only when a real need comes up. You do not need to buy every tool or course recommended in a sales pitch.
Is Wealthy Affiliate worth the cost for retirees?
It depends on your budget, how you prefer to learn, and what the membership includes when you check it. Try the free Starter membership first. Then review current prices, renewal costs, included features, and cancellation terms on the official membership page. Consider it only if the cost fits your spending ceiling.
How long should I try an online business before reassessing?
Choose a review date in advance. A content-based business can take months to attract readers, so a few weeks may not tell you much. Pick a period that suits your finances, multiply your monthly ceiling by the number of months, and review your spending, completed work, and any income on that date.
Do I have to report income from an online business?
Tax rules depend on where you live and your situation. Check with a tax professional or the relevant government agency before you earn. If you receive Social Security benefits, contact the Social Security Administration to ask how work and earnings may affect your benefits.